4.1 Terms Used in Money and Banking
The terminology used in money and banking is specialized and often technical, yet office administrators must be conversant with these terms to perform their duties efficiently. Each term reflects an aspect of how money circulates, how financial institutions operate, and how monetary policy impacts business environments in Kenya.
4.1.1 Liquidity
Liquidity is a crucial financial concept that affects both individuals and organizations, including offices and businesses across Kenya. It refers to the ease with which assets can be converted into cash without significant loss of value, enabling smooth financial operations.
Meaning of Liquidity
Liquidity describes the availability of cash or assets that can quickly be turned into cash to meet immediate financial obligations. For example, a company with high liquidity can pay salaries and suppliers promptly, avoiding operational disruptions.
Types of Liquidity
- Market Liquidity: Refers to how easily assets like shares or bonds can be sold at stable prices in the market.
- Accounting Liquidity: Indicates the ability of an entity to meet short-term liabilities using current assets.
- Funding Liquidity: The capacity to access cash or credit when needed, such as through bank overdrafts.
- Operational Liquidity: Relates to the cash flow generated from daily business activities.
- Systemic Liquidity: The overall liquidity available in the banking system, influenced by central bank policies.
Importance of Liquidity in Office Administration
Liquidity ensures that an organization can cover payroll, pay vendors, and manage unexpected expenses without delays. For instance, county government offices rely on liquidity to maintain uninterrupted service delivery and procurement processes.
Measures of Liquidity
Common measures include the current ratio (current assets divided by current liabilities) and quick ratio (excluding inventory from current assets). These ratios help assess an organization's short-term financial health.
Factors Affecting Liquidity
- Cash Reserves: Adequate cash holdings improve liquidity.
- Credit Facilities: Access to loans or overdrafts enhances liquidity options.
- Inventory Levels: Excess inventory can reduce liquidity as it ties up cash.
- Receivables Collection: Efficient collection of payments increases available cash.
- Economic Conditions: Inflation and market fluctuations can influence liquidity.
4.1.2 Monetary Policies
Monetary policies are strategies implemented by central banks to regulate money supply and interest rates, impacting economic stability. In Kenya, the Central Bank of Kenya (CBK) plays a pivotal role in shaping monetary policy to foster growth and control inflation.
Definition of Monetary Policies
Monetary policies involve deliberate control of money supply, credit availability, and interest rates to achieve macroeconomic objectives such as price stability, full employment, and sustainable growth.
Types of Monetary Policies
- Expansionary Policy: Increases money supply to stimulate economic growth, often through lowering interest rates.
- Contractionary Policy: Reduces money supply to control inflation by raising interest rates.
- Neutral Policy: Maintains current money supply levels to sustain economic equilibrium.
- Monetary Targeting: Focuses on controlling money supply growth rates.
- Inflation Targeting: Aims at maintaining inflation within a specified range.
Instruments of Monetary Policy
- Open Market Operations: Buying or selling government securities to influence liquidity.
- Bank Rate Adjustments: Changing the rate at which banks borrow from the central bank.
- Cash Reserve Ratio: Percentage of deposits banks must hold as reserves.
- Moral Suasion: Persuading banks to adhere to policy guidelines.
- Credit Rationing: Limiting the amount of credit available to certain sectors.
Effects of Monetary Policies on Office Administration
Monetary policy influences borrowing costs, investment decisions, and cash management in offices. For example, a rise in interest rates may increase loan repayments for office projects, necessitating budget adjustments.
Role of CBK in Monetary Policy Implementation
The Central Bank of Kenya monitors inflation, exchange rates, and banking sector liquidity to adjust policies accordingly, ensuring a stable financial environment that supports businesses and public institutions.
4.1.3 Plastic Money
Plastic money refers to electronic payment methods replacing cash transactions, providing convenience and security in financial dealings. For office administrators, understanding plastic money is essential for managing payments and receipts digitally.
Definition of Plastic Money
Plastic money includes credit cards, debit cards, prepaid cards, and other electronic payment instruments enabling cashless transactions.
Types of Plastic Money
- Credit Cards: Allow users to borrow funds up to a credit limit for purchases.
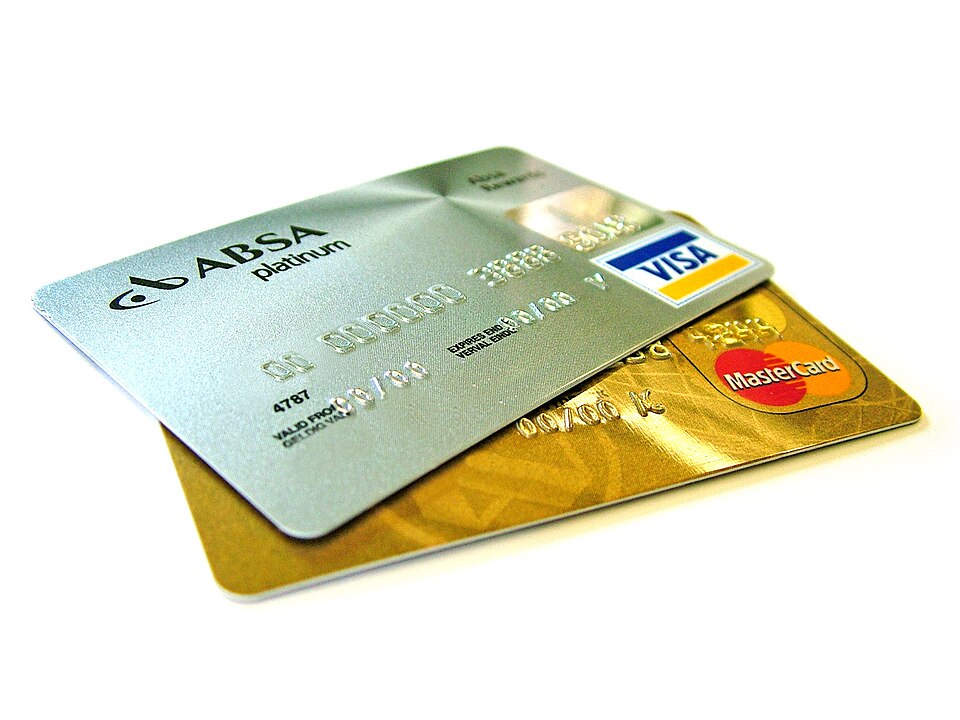
Two credit cards showing Visa and MasterCard logos (Source: Wikimedia Commons (Credit card))
- Debit Cards: Deduct funds directly from the user's bank account.
- Prepaid Cards: Loaded with a fixed amount of money for spending.
- Charge Cards: Require full payment of the balance at the end of the billing cycle.
- Electronic Wallets: Digital accounts linked to cards or bank accounts.
Advantages of Plastic Money
- Convenience: Enables quick payments without carrying cash.
- Security: Reduces risks of theft or loss associated with cash.
- Record Keeping: Transactions are automatically recorded, aiding financial management.
- Accessibility: Facilitates online and offline purchases.
- Credit Facility: Credit cards offer borrowing options for short-term needs.
Challenges of Using Plastic Money
- Fraud Risks: Susceptibility to unauthorized transactions.
- Acceptance Issues: Not all vendors may accept plastic money, especially in rural areas.
- Transaction Fees: Charges on card usage may increase costs.
- Technical Problems: System outages can disrupt transactions.
- Dependency on Technology: Requires access to electronic devices and internet.
4.1.4 Bank rate
The bank rate is a critical interest rate used by central banks to influence economic activity. Understanding how bank rates are assessed helps office administrators anticipate changes in borrowing costs.
Meaning of Bank Rate
The bank rate is the interest rate at which the central bank lends money to commercial banks, affecting overall interest rates in the economy.
Factors Influencing Bank Rate Assessment
- Inflation Levels: High inflation may prompt an increase in bank rates.
- Economic Growth: Slower growth may lead to lower bank rates to stimulate borrowing.
- Currency Stability: To maintain exchange rate stability, bank rates may be adjusted.
- Fiscal Policy: Government borrowing needs can influence bank rate decisions.
- Global Economic Conditions: External shocks may necessitate rate changes.
Impact of Bank Rate Changes on Businesses
An increase in bank rate raises loan interest expenses for businesses, affecting cash flow and investment plans. For example, a retail business in Nairobi may delay expansion if borrowing costs rise.
Role of CBK in Bank Rate Determination
The Central Bank of Kenya regularly reviews economic data and sets the bank rate to balance inflation control and economic growth.
4.1.5 Microfinance
Microfinance institutions provide financial services to individuals and small businesses often excluded from traditional banking, playing a vital role in Kenya’s economic inclusion.
Definition of Microfinance
Microfinance encompasses small loans, savings, insurance, and other financial products targeted at low-income populations or small enterprises.
Services Offered by Microfinance Institutions
- Microloans: Small credit amounts for business or personal use.
- Savings Accounts: Encouraging savings with low minimum balances.
- Microinsurance: Affordable insurance products tailored to low-income clients.
- Money Transfers: Facilitating remittances and payments.
- Financial Education: Training clients on money management.
Importance of Microfinance in Kenya
Microfinance supports entrepreneurship and poverty reduction by providing capital to informal sector businesses such as small-scale farmers and shopkeepers.
Challenges Facing Microfinance Institutions
- High Operational Costs: Serving many small clients increases expenses.
- Credit Risk: Borrowers may default due to unstable incomes.
- Regulatory Compliance: Adhering to banking regulations can be complex.
- Limited Outreach: Rural areas remain underserved.
- Competition: Banks and mobile money providers offer overlapping services.
4.1.6 Mobile Banking
Mobile banking revolutionizes financial access in Kenya, especially through platforms like M-Pesa, enabling transactions via mobile phones.
Definition of Mobile Banking
Mobile banking allows users to perform financial transactions using mobile devices without visiting physical bank branches.
Services Available through Mobile Banking
- Funds Transfer: Sending and receiving money locally and internationally.
- Bill Payments: Paying utilities, school fees, and other bills.
- Account Management: Checking balances and transaction history.
- Loan Applications: Accessing credit facilities via mobile platforms.
- Savings Products: Opening and managing savings accounts.
Benefits of Mobile Banking for Office Administration
Mobile banking enhances payment efficiency, reduces cash handling risks, and supports remote financial management for institutions such as universities and hospitals.
Security Considerations in Mobile Banking
- PIN Protection: Ensuring strong personal identification numbers.
- Two-Factor Authentication: Additional verification steps for transactions.
- Fraud Monitoring: Systems to detect unusual activity.
- User Education: Training staff on safe usage practices.
- Data Privacy: Protecting personal and financial information.
4.1.7 Bank Ombudsman
The bank ombudsman is an independent authority that resolves disputes between banks and their customers, ensuring fair treatment in the banking sector.
Role of the Bank Ombudsman
The ombudsman investigates complaints related to bank services, such as unfair charges, denied loans, or poor customer service.
Procedures for Filing Complaints
- Submission: Customers submit complaints in writing or online.
- Acknowledgment: The office confirms receipt and starts investigation.
- Mediation: Efforts to resolve disputes amicably between parties.
- Decision: Issuance of a binding or advisory ruling.
- Appeal: Options to contest decisions in courts if necessary.
Importance of the Bank Ombudsman in Kenya
The ombudsman promotes trust in the banking system, protecting consumers and small businesses, such as SACCO members, from unfair practices.
Limitations of the Bank Ombudsman
The ombudsman cannot handle criminal cases, disputes outside banking services, or complaints after statutory time limits.
4.1.8 Linked Account
A linked account connects two or more bank accounts or financial services, facilitating seamless transactions and fund management.
Definition of Linked Account
Linked accounts enable direct transfers and payments between accounts without manual intervention, improving financial efficiency.
Common Types of Linked Accounts
- Savings and Current Account Linkage: Allows overdraft protection or automatic transfers.
- Mobile Wallet and Bank Account: Enables topping up mobile money from bank accounts.
- Business Accounts and Payment Gateways: Supports e-commerce transactions.
- Payroll Accounts Linked to Salary Accounts: Simplifies salary disbursement.
- Investment and Savings Accounts: Facilitates fund movement for investment purposes.
Benefits of Linked Accounts for Office Administration
Linked accounts reduce transaction delays, enhance cash flow management, and simplify reconciliation processes in institutions like county governments.
Risks Associated with Linked Accounts
- Unauthorized Transfers: Risk of fraud if access controls are weak.
- System Failures: Technical issues can disrupt linked transactions.
- Overdraft Risks: Automatic transfers may lead to unplanned overdrafts.
- Complexity in Management: Requires careful monitoring to avoid errors.
- Data Privacy Concerns: Sharing information across linked accounts needs secure systems.
4.1.9 Base Rate
The base rate is the minimum interest rate set by banks below which they cannot lend, influencing lending practices and credit availability.
Meaning of Base Rate
The base rate is a benchmark interest rate that banks use to price loans, reflecting their cost of funds and risk premium.
Determination of Base Rate
Banks consider factors such as central bank rates, cost of deposits, operational expenses, and credit risk when setting base rates.
Impact of Base Rate on Borrowers
A higher base rate increases borrowing costs, affecting loan affordability for businesses and individuals, including office equipment financing.
Regulatory Framework on Base Rates in Kenya
The Central Bank of Kenya mandates transparency in base rate setting to protect consumers and promote fair lending.
Difference Between Base Rate and Bank Rate
While the bank rate is set by the central bank for commercial banks, the base rate is set by individual banks for lending to customers.
Practice Questions
- Explain the concept of liquidity and its importance to office administration in Kenyan organizations. (10 marks)
- Describe five instruments of monetary policy used by the Central Bank of Kenya and their effects on businesses. (15 marks)
- Discuss the advantages and challenges of using plastic money in office financial transactions. (10 marks)
- Outline the role of the bank ombudsman in protecting bank customers and the procedures for filing a complaint. (10 marks)
- Differentiate between the bank rate and base rate, including their implications for loan borrowers. (10 marks)
The rest of this chapter
🔒Create a free account to open more of this chapter.
Free: practical guides, quick cards, workplace scenarios and more.
Create a free account 🔒4.2 Characteristics of Money
Money is a fundamental element in commerce and office administration, acting as a common denominator in transactions across Kenya's diverse economic sectors. Understanding the characteristics of money helps office administrators manage financial records, proce…
🔒4.3 Functions of Money
Money performs several vital functions that underpin commerce and office administration in Kenya. Its role extends beyond mere currency to acting as a standard for valuing goods and services, facilitating exchange, storing wealth, and enabling deferred payment…
🔒4.4 Types of Banks
In Kenya's financial landscape, various types of banks serve distinct roles that support economic activities and financial management. Office administration professionals often interact with different banks depending on their organisation’s needs, such as sala…
🔒4.5 Types of Bank Accounts
Office administration professionals must understand the various types of bank accounts to manage organisational finances effectively. Selecting the appropriate account type influences liquidity, interest earnings, and transaction convenience for both individua…
🔒4.6 Functions of Commercial Banks
Commercial banks play a critical role in Kenya’s financial system and economy, serving as intermediaries between depositors and borrowers. For office administration professionals, understanding these functions is essential for managing financial transactions,…
🔒4.7 Functions of Central Bank
The Central Bank of Kenya (CBK) is the apex monetary authority responsible for regulating the country’s banking sector and formulating monetary policy. For office administration professionals, knowledge of the central bank’s functions is crucial when dealing w…
Chapter Summary
This chapter introduced key terms in money and banking such as liquidity, monetary policies, plastic money, bank rate assessments, microfinance, mobile banking, bank ombudsman-linked accounts, and base rate, establishing a foundation for understanding financial systems. It then explored the essential characteristics of money including durability and limited supply, which ensure its effectiveness as a medium of exchange. The functions of money were discussed, highlighting its role as a measure of value and an exchange medium among others. Different types of banks were outlined, focusing on the central bank and various commercial banks like Cooperative Bank and Equity Bank. The chapter also examined the types of bank accounts available, including current, savings, and fixed deposit accounts, each serving different financial needs. The functions of commercial banks were explained, emphasizing deposit acceptance and lending activities. Finally, the role of the central bank was covered, particularly its responsibility in controlling inflation to maintain economic stability.
Self-Assessment
🔒 PDFDownload this self-assessment, with answers
A. Written Assessment
- Define liquidity and explain its importance in banking (3 marks)
- What is plastic money? Give two examples commonly used in Kenya (3 marks)
🔒20 more in this section.
Chapter Examination Questions
🔒 PDFDownload these examination questions, with worked answers
SECTION A (40 Marks) - Answer ALL Questions
- Define liquidity and explain its importance for an office administrator managing petty cash in a county government office. (4 marks)
- Describe two monetary policies used by the Central Bank of Kenya to control inflation. (4 marks)
🔒18 more in this section.
